MEANING OF NIL RATED SUPPLY UNDER GST
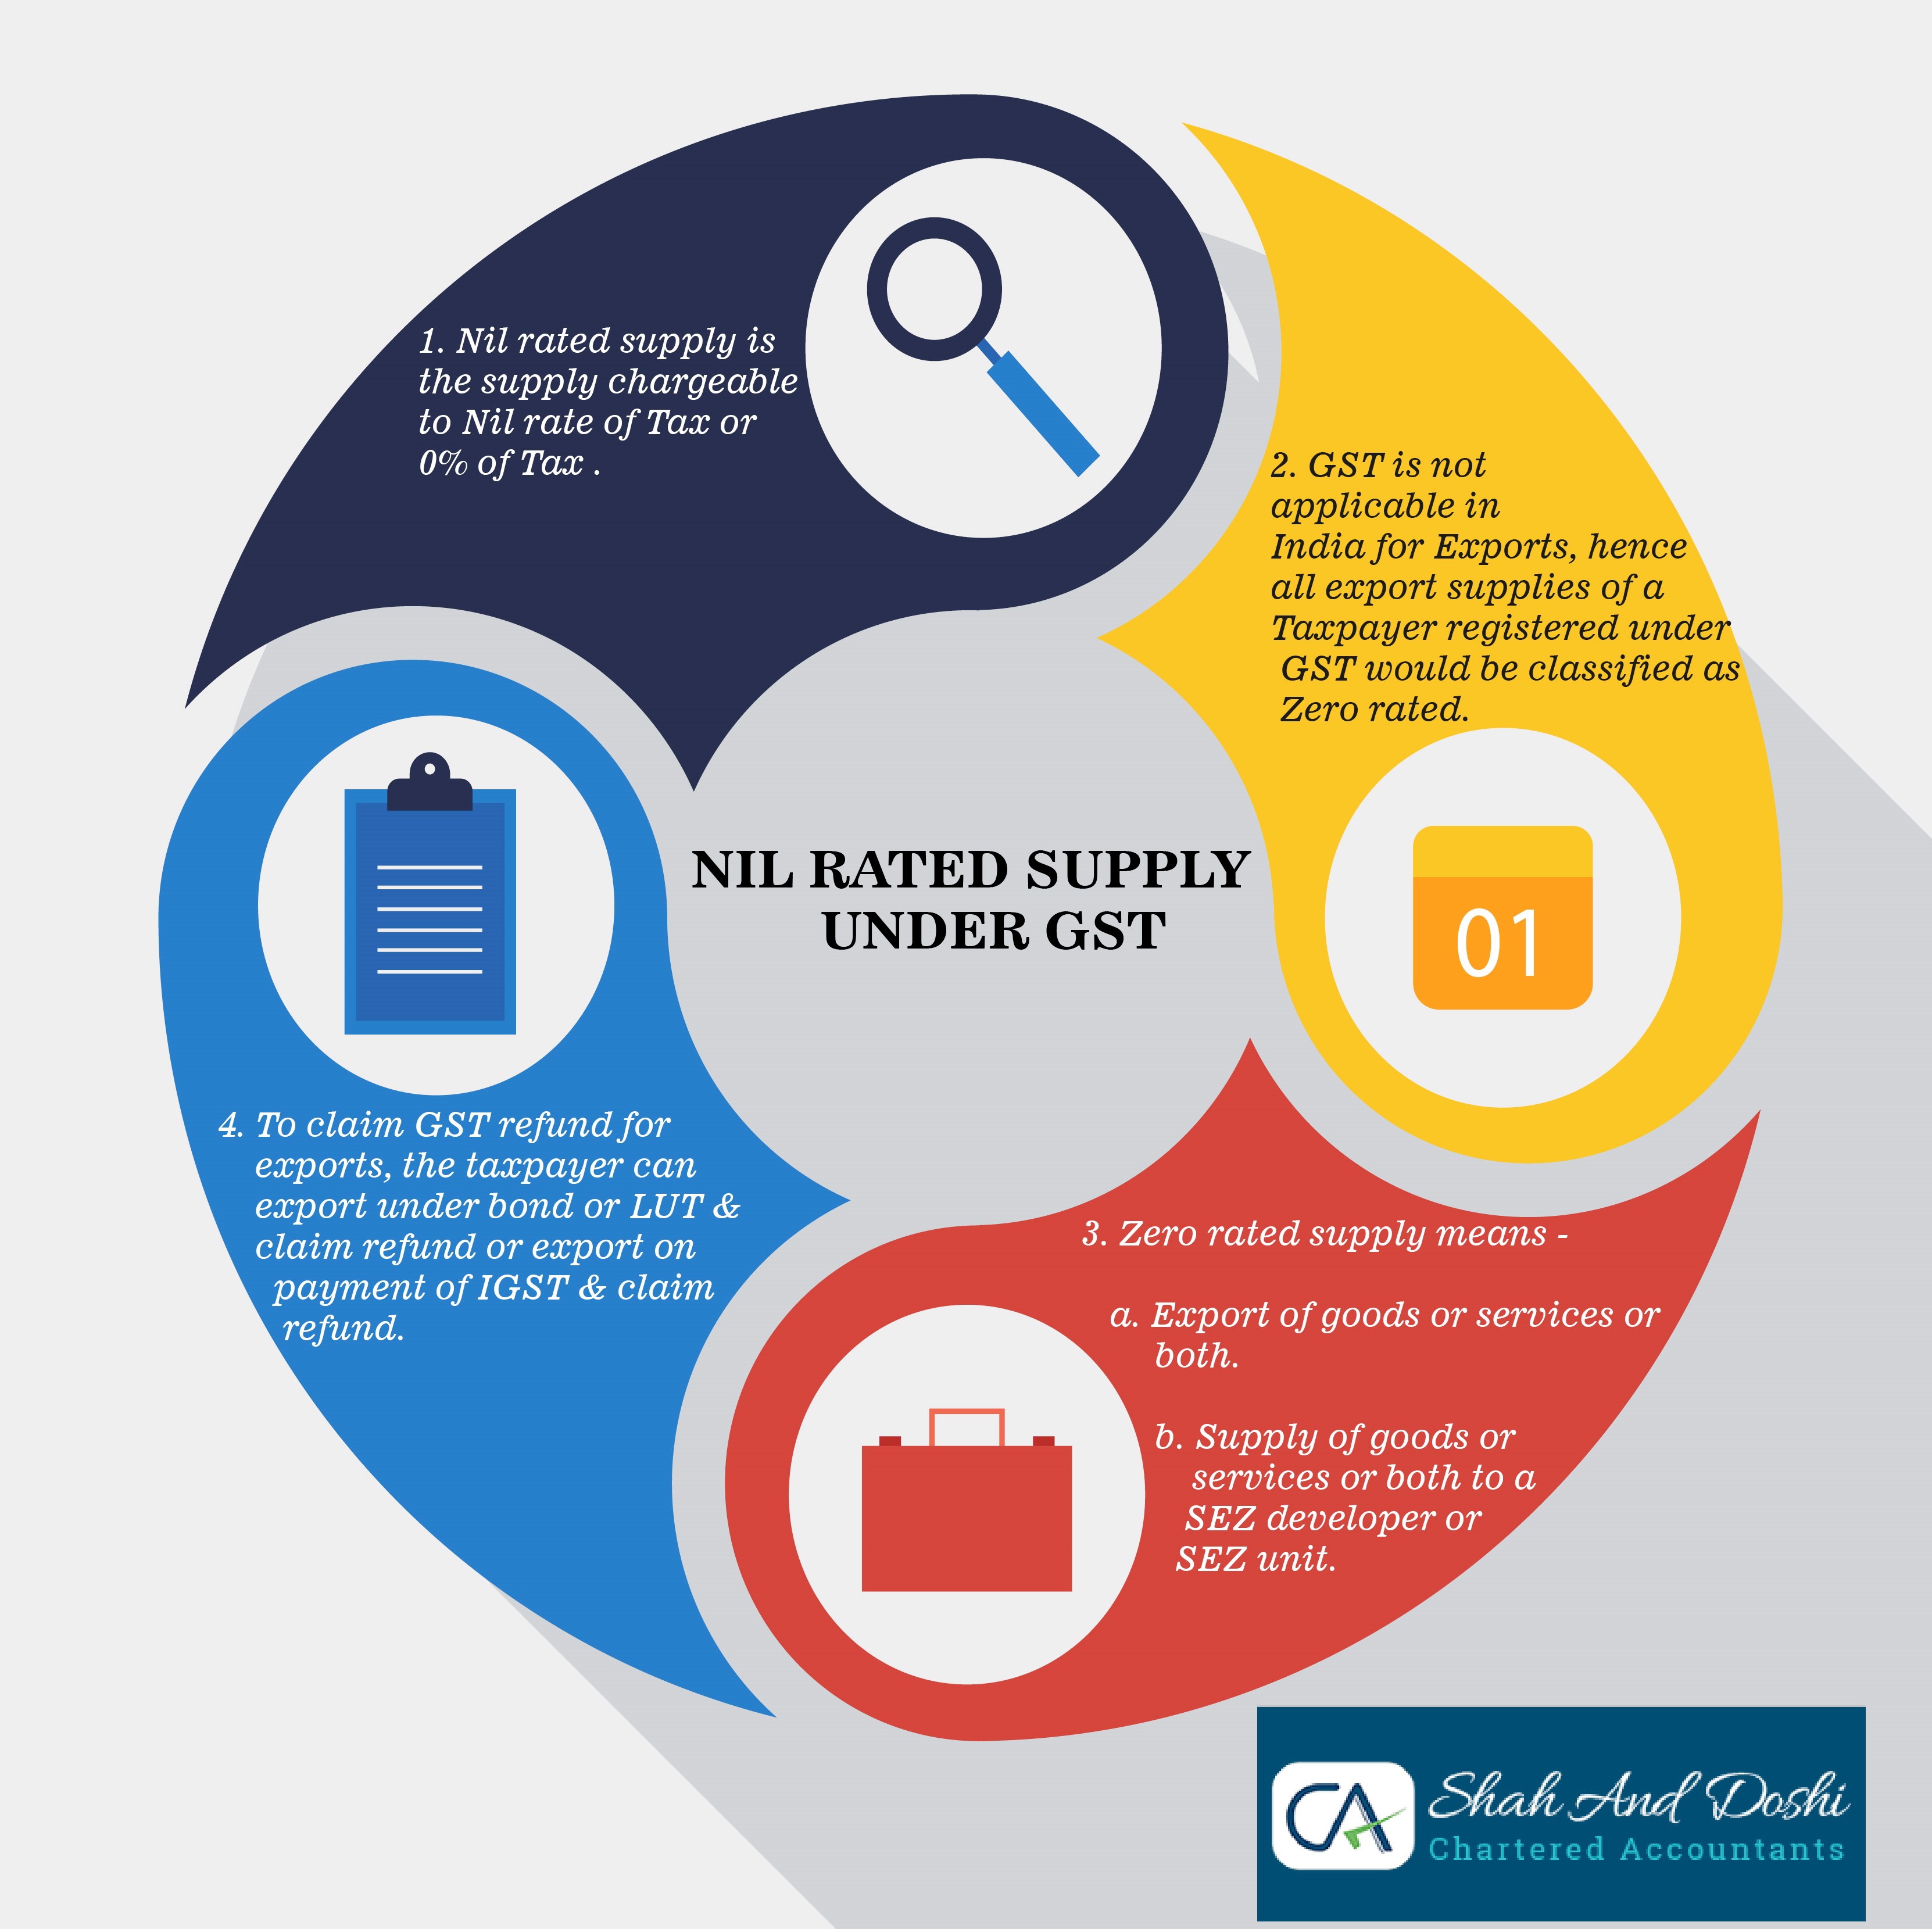
Nil rate or 0% is the rate of tax on the output supplies. Sales of Nil rated goods to a Local or Inter-state Consumer does not attract GST. Exempt supplies include Nil rated supplies (taxable at 0%) & Non-taxable supplies.
Individuals who deal exclusively in Nil rated or Exempt goods/services i.e. 100% exempt supplies are not liable to register under GST, irrespective of the turnover being more than 20 Lakhs or 10 Lakhs.
– if the tax is Nil, set off (Input tax credit) is NOT available on the tax paid on the input supplies.
– set off (Input Tax Credit) is available in zero-rated supplies where the output tax is zero.
This is similar to the pre taxation regime of Excise or VAT.
EXPORTS –
GST is not applicable in India for Exports. Export supplies of a taxpayer registered under GST are treated as zero-rated supplies.
Section 16 of the IGST Act, zero-rated supply means any of the following as supplies of goods or services:
- Export of Goods & services or Both.
- supply of Goods or services or Both to an SEZ Developer.
- supply of Goods or services or Both to an SEZ Unit.
Exports being zero-rated supply, the supplier is eligible to claim an input tax credit in respect of goods or services used for the supplies even though they might be non-taxable or even exempt supplies.
To claim GST refund for exports, the taxpayer can export under bond or LUT and claim refund or export on payment of IGST and claim a refund.